Table of Contents
⚖️ DISCLAIMER: This video is for educational and informational purposes only and does not constitute legal advice. If a large sum of money or business account is involved, consider consulting a qualified lawyer.
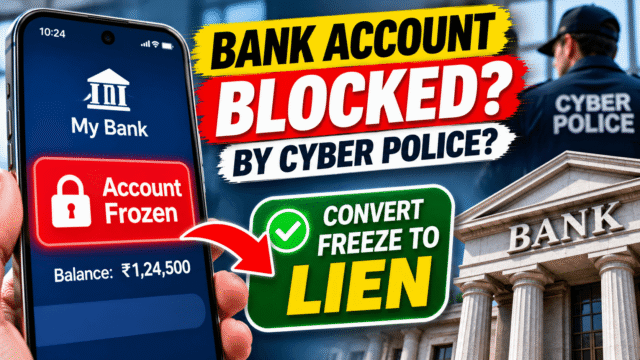
Your UPI payment fails. Your debit card is declined. You call the bank and they tell you your account has been frozen, or a lien has been marked, because of a cyber crime complaint. You haven’t scammed anyone. You might have sold something online, received a payment from a client, or sold crypto to a stranger. Somewhere along the way, money from a fraud passed through your account.
This is happening to thousands of ordinary people across India. The good news is that there’s now an official process for it, and courts have repeatedly said that banks and police shouldn’t lock an entire account over a small disputed amount.
Here’s what’s happened, what to ask your bank, and how to get your money released. This guide explains the process; it isn’t legal advice, and for large amounts you should speak to a lawyer.
Why your account was frozen
When someone is cheated online in India, they report it on the National Cyber Crime Reporting Portal (cybercrime.gov.in) or by calling 1930. The complaint goes into a system run by the Indian Cyber Crime Coordination Centre (I4C) under the Home Ministry. Police and banks then follow the stolen money from account to account and ask each bank to hold it.
Scammers move money quickly, through several accounts. If money from a fraud reached your account, even indirectly and even as payment for something real, your account can be flagged. That’s why innocent people get caught: a buyer paid you with stolen money, a crypto trade partner used fraud proceeds, or a client’s payment came from a mule account.
Lien, debit freeze or total freeze: what has your bank done?
These terms get used loosely, but they mean different things:
- Lien on an amount: a specific sum, usually the disputed amount, is blocked. You can use the rest of your balance normally.
- Debit freeze: you can receive money but can’t take any out.
- Total freeze: nothing goes in or out.
Ask your bank which one it is and how much is blocked. It matters, because the rules now say the hold should usually be limited to the disputed amount.
Step 1: Get the details from your bank, in writing
Banks often send a vague SMS or say “cyber cell instruction” and nothing more. You need specifics. Visit your branch, or write to the bank’s grievance email, and ask for:
- The authority that asked for the hold: which police station or cyber cell, and in which state
- The complaint or acknowledgement number from the cyber crime portal
- The date of the instruction
- The exact amount on hold, and whether it’s a lien on that amount or a freeze on the whole account
- The transaction in your account that was flagged
Ask for this in writing or by email, and keep copies of everything. The complaint is often registered in a different state from where you live, so the police station name and complaint number are what let you act.
Step 2: Work out which transaction caused it, and gather proof
Find the flagged credit in your bank statement. Then collect anything that shows why you received it and that it was legitimate:
- Invoices, bills or a sale agreement
- WhatsApp or email conversations with the person who paid you
- Screenshots from the marketplace, app or platform where the deal happened
- Crypto exchange trade records, if it was a peer-to-peer crypto sale
- Proof you delivered the goods or service
- Your ID and KYC documents
The stronger your paper trail, the faster this goes. Your aim is to show you received the money in good faith, for something real.
Step 3: Raise a grievance through your bank
Under the Home Ministry’s standard operating procedure (SOP) dated January 2, 2026, there’s now an official grievance system for people whose accounts are held. It runs through I4C’s grievance module on the cyber crime portal, but you start it at your bank.
- Go to your bank branch and apply to have the hold removed or reduced. Take your ID, the details from Step 1 and the proof from Step 2.
- The bank checks your KYC and transaction history.
- The bank registers your grievance on the online grievance module and gives you a Grievance ID. Under the SOP, it should do this within 7 days.
- The investigating officer at the police station that asked for the hold reviews it. The officer may record your statement over video call. Under the SOP, they should decide within 15 days.
- If the officer doesn’t act within 15 days, the system escalates the case to a District Grievance Officer automatically.
- If your grievance is rejected, you can appeal to the District Grievance Officer within 15 days, and after that to the State Grievance Officer.
Ask your bank for the Grievance ID and note every date. If the branch says it doesn’t know about this process, ask for the bank’s nodal officer or grievance officer for cyber fraud cases. In August 2026, the Allahabad High Court told banks in Uttar Pradesh to follow this grievance mechanism and to make it visible to customers at branches and online.
The SOP also includes a 90-day rule, but it doesn’t cover everyone. Legal analyses of the SOP say it applies to smaller disputed amounts, below ₹50,000. In those cases, if no court order or other lawful direction extends the hold within 90 days, the bank can lift it on your request, as long as the police haven’t asked for more time and the money isn’t needed in another case. If your disputed amount is below ₹50,000 and the hold has dragged on, ask your bank about it. If a larger amount is held, don’t expect an automatic release. You’ll need the grievance route or a court order.
Step 4: Contact the investigating officer directly
In parallel, it often helps to contact the police station or cyber cell named by your bank.
- Find the station’s official phone number or email on the state police website.
- Write a short, clear email: your name, account number, the complaint number, the amount on hold, how you received the money, and a request to release or limit the hold to the disputed amount. Attach your proof.
- If asked, appear in person or join a video call, and answer questions truthfully.
Keep everything in writing where you can, and keep a copy of every email.
Ask for the hold to be limited to the disputed amount
If your whole account is frozen over a small amount, ask the bank and the investigating officer to convert it into a lien on the disputed amount only.
You’re on solid ground here. The Home Ministry’s SOP says a lien should be limited to the disputed sum. Several High Courts have said the same. In August 2026, the Allahabad High Court told banks to follow the SOP and held that a lien can’t extend beyond the specific disputed amount. The Rajasthan High Court said the same month that the normal course should be to hold the amount in question and let the account holder use the rest: freeze the amount, not the account. And the Madhya Pradesh High Court ordered a bank to unfreeze a woman’s account, keep only the disputed sum in a fixed deposit, and let her withdraw it if the police didn’t act within three months.
Courts don’t all agree on every detail. In August 2026, the Karnataka High Court said police can debit-freeze an account during an investigation without a prior court order, as long as they report it to the magistrate. But the direction across courts and the SOP is clear: a total freeze over a small disputed sum is the exception, not the rule.
Step 5: When to go to court
If the grievance route and the police don’t help, you can apply to court. Common routes are:
- An application to the magistrate’s court that handles the case, asking for the money or account to be released
- A writ petition in your High Court, especially if your whole account is frozen without a specified amount, or the hold has gone on for months with no action
Both need a lawyer. It’s usually worth it if a large sum is blocked, if a business account is frozen, or if months have passed with no response. Check that the lawyer has handled account-freeze cases before, and ask for their fees upfront.
Beware of anyone offering to “unfreeze” your account for money
Once your account is frozen, you may get calls from people claiming to be from the cyber cell, the CBI or the bank. They say they can release your account if you pay a “clearance fee” or transfer money to a “verification account”. Some threaten arrest.
This is a scam. Real police don’t ask you to pay money to unfreeze an account, and nobody can arrest you over a video call. Check any police contact yourself, using the number from the official police website, and never pay anyone to remove a freeze. If you’re targeted, report it on 1930 or at cybercrime.gov.in.
Also be wary of people online who promise guaranteed unfreezing within a day. The official process is free.
What’s changing next
In August 2026, the Supreme Court told the RBI to prepare a standard procedure for bank accounts linked to cyber fraud. In September, the RBI published a draft. If it’s finalised as drafted, banks would have to tell customers when they place a hold, explain why and how to get it removed, and limit their own holds to 60 days unless the police or another competent authority say otherwise. Holds on the whole account would be a last resort. You’d get 20 days to explain the transaction, and the bank would have to decide within 10 days of your explanation. The draft is open to change, and the proposed start date is April 1, 2027.
How to avoid this happening again
- Be careful accepting money from strangers, especially for high-value second-hand sales. Use the marketplace’s own payment system where you can.
- Avoid peer-to-peer crypto trades with people you don’t know. They’re one of the most common reasons innocent accounts get frozen.
- Never let anyone use your bank account or UPI to receive money for them, even for a “commission”. Accounts used this way are called mule accounts, and lending yours is a crime.
- Never accept “part-time job” or “task” offers that involve receiving and forwarding money.
- If an unexpected payment lands in your account, don’t spend or forward it. Contact your bank.
- Keep records of every significant payment you receive, so you can prove where it came from.
Quick Answers
Why is my bank account frozen after a cyber complaint?
Money linked to an online fraud reached your account, directly or through other accounts. Police asked your bank to hold it while they investigate. It doesn’t mean you’re accused of the fraud.
How do I unfreeze my bank account frozen by cyber crime?
Get the complaint number, police station and amount from your bank, gather proof the money was legitimate, and ask your bank to raise a grievance on I4C’s grievance module. If that fails, appeal to the District and State Grievance Officers, or apply to court.
Can police freeze my entire bank account for a small amount?
The Home Ministry’s 2026 SOP and several High Courts say the hold should usually be limited to the disputed amount. Ask your bank to convert a full freeze into a lien on that amount.
How long does a cyber lien on a bank account last?
There’s no single fixed time. For disputed amounts below ₹50,000, the 2026 SOP lets the bank lift the hold on request after 90 days if no court order or lawful direction extends it, subject to conditions. For larger amounts, it can last until the investigation ends or a court orders release, so use the grievance route or approach a court.
What is the difference between a lien and a freeze?
A lien blocks a specific amount, and you can use the rest. A debit freeze stops withdrawals. A total freeze blocks everything.
Someone called saying they can unfreeze my account for a fee. Is it real?
No. Real police and banks don’t charge to unfreeze accounts. It’s a scam. Report it on 1930 or at cybercrime.gov.in.
Sources:
- Medianama: MP High Court sets a 3-month limit
- LiveLaw: Reading MHA’s new account-freeze SOP (₹50,000 and 90 days)
- LiveLaw: Allahabad HC on the disputed-amount lien and the SOP
- Verdictum: Bombay HC (Kartik Yogeshwar Chatur v Union of India)
- Business Standard: RBI draft on 60-day holds